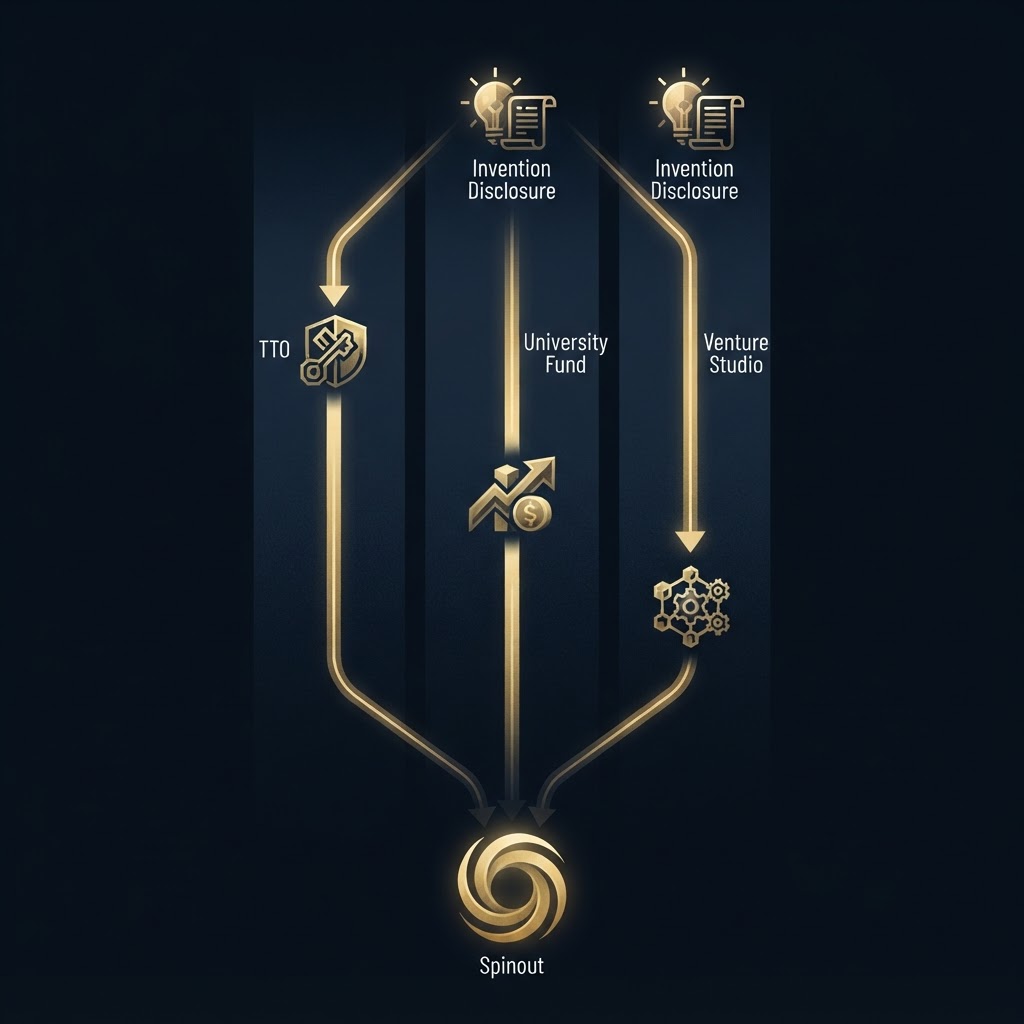
A university venture studio is the newest answer to an old problem: most patented research never becomes a company. The technology transfer office files the patent and waits for a licensee. The university fund writes a cheque once a startup exists. Neither of them builds anything. The studio does, and that single difference changes who is in the room, how long the clock runs, and what is left undone when the programme ends.
This piece explains the model, puts it next to the two older ones, shows how the two best-documented US programmes actually run, and names the part of the job that no university studio has a mandate to finish.
What a university venture studio actually does
The clearest definition comes from a guide written for research administrators: a university venture studio is a company-building operation, usually staffed with its own full-time venture builders, engineers and operators, that proactively identifies research with commercial potential and works alongside faculty to found new companies around it, rather than waiting for a licensee or investing in a startup a professor has already started.
Three words carry the definition. Proactive: the studio goes into the lab instead of waiting for an invention disclosure. Embedded: the people doing the work are employed to do it full time. Pre-formation: the studio works before there is a company for anyone else to evaluate.
The model is young. MIT opened the first venture studio of its kind within a university in 2019, and in 2025 published a playbook so that other universities, national labs and corporate R&D offices could copy it. The University of Texas at Austin is cited in the same piece as following the model.
Studio, TTO or university fund: three models side by side
The guide above is careful to say the three are increasingly deployed together rather than as substitutes. The difference is not the money. It is the operating team.
| Technology transfer office | University fund | University venture studio | |
|---|---|---|---|
| Enters when | Invention is disclosed | Company already exists | Before a company exists |
| Owns | The patent, the license | An equity stake | The build process |
| Supplies | Legal and administrative work | Capital and board seats | Venture builders, engineers, a CEO search |
| Who builds | A licensee or a faculty founder | The founder | The studio with the inventor |
Where each model enters
A TTO evaluates a disclosure, decides whether to patent, then markets the IP. A fund waits for a priced round. A studio starts earlier than both: it scouts labs, picks a real-world problem the research could solve, and recruits the founding CEO. We compared the first and third of these in depth in venture studio vs technology transfer office.
Who does the building
In the TTO model the licensee builds. In the fund model the founder builds. In the studio model the studio builds alongside the inventor, which is why the studio can act on research whose inventor has no interest in leaving the lab. That is the case the older models cannot touch.
How the leading programmes run
MIT Proto Ventures: channels and venture builders
MIT's process starts with a channel, a problem or technology space such as fusion, clean energy or AI in health care. MIT then hires a full-time venture builder with deep technology and translation experience to lead discovery in that channel, who spends roughly six months searching for opportunities before forming teams with venture fellows, often post-docs, to de-risk the best fits technically and commercially. The survivors become independent ventures.
The numbers from inside one channel show what embedding means in practice. The venture builder at the Plasma Science and Fusion Center reports having engaged 75 researchers in translational activities, many for the first time, with early ventures in superconducting-magnet satellite propulsion and data-centre power supplies. The same interview is blunt about why the studio exists: turning MIT research into a startup used to take a great deal of serendipity, and most researchers lack the time, incentives or skills to commercialise.
The programme is sponsor funded. Sponsor organisations, corporations and philanthropic donors, get access to people, ideas and technologies across MIT, and the current channel is geothermal.
Tulane Founder Lab: entrepreneurs-in-residence paired with patents
Tulane's version flips the staffing. Instead of hiring builders, it recruits experienced founders as paid entrepreneurs-in-residence and pairs them with faculty technology. The first cohort, launched in August 2025, matched four EIRs with four faculty researchers in a compressed six-month programme with an on-ramp to Tulane Ventures, with EIRs whose backgrounds include a $675 million medtech acquisition.
Year two is the more instructive story because the design changed. The first EIRs asked to see more of the portfolio before committing, so Tulane added an evaluation stage: one EIR pair reviewed about 18 patents or groups of related patents, ranked them individually, narrowed the field as a group, then focused on one. The same report notes a four-year $6 million National Science Foundation grant behind the commercialisation push and a $10 million Tulane Ventures fund. The next six-month cohort starts on 24 September 2026.
Two lessons travel. A studio that screens 18 patents to build one company is running a funnel, not a pairing service, and the width of that funnel is the real capacity number. And a studio that revises its own process after one cohort is behaving like a startup, which is the right posture.
In-house studio or external partner
The MIT playbook argues hard for the in-house version. Its reasoning is that venture builders must embed in labs day in and day out, which is hard if the studio is a separate entity, and that an internal studio can use the TTO, seed grants, mentorship and maker spaces that an outside studio would struggle to access. It names the alternative too: formal agreements between an institution and a for-profit studio, such as Oxford University with Oxford Science Enterprises or Woods Hole with Propeller.
The argument is fair as far as it goes. An in-house studio sees more and is trusted more. Its limit is scope. It is funded by sponsors or grants to form companies from one institution's research, and its mandate ends when the venture spins out. For software that is enough. For hardware it is the halfway point.
Where a university studio stops, and what comes next
Formation is not deployment
Every programme above measures success at the first external funding round or the spinout. A waste-to-energy unit, a biomanufacturing line or a power supply for a data centre then needs financing, manufacturing partners, permits in each country and operators on site. That is a second company-building job, and it is the one a deep-tech venture builder exists to do.
EX EPIC's own numbers show the shape of that second job. The group has a capital track record above EUR 160 million and has designed, financed and installed more than 200 waste-to-energy units across 11 countries. None of that work happens inside a university, and none of it is covered by a six-month programme.
Patents in one country are not a global position
A university studio works from the institution's patent, usually filed in its home jurisdiction. Deploying on four continents requires a patent strategy built for the markets where the hardware will run. EX EPIC's IP arm has 24 patent families filed and roughly 100 more validated in its pipeline, and its Academy has placed more than 250 operators into the portfolio, the staffing layer no studio provides after spinout. Our guide to how to commercialize university research covers how the licensing step connects to that wider plan.
The honest summary: a university venture studio solves the formation problem that TTOs and funds left open. The deployment problem is still open, and it is where an external builder earns its place without competing with the studio at all.
Questions to ask before joining or partnering with one
- Who owns what at the end? The institution keeps the patent and licenses it to the new company. Ask what equity the university takes and whether the EIR or venture builder becomes a founder with a stake.
- Who chooses the channel? At MIT a sponsor can propose one. If your research sits outside the current channel, the studio may not look at it this year.
- What is the clock? Six months is the stated length at both MIT's search phase and Tulane's programme. Know what has to be true at month seven.
- What does the studio do after spinout? Usually a handoff to accelerators and licensing. Line up the deployment partner before that handoff, not after. Our guides to how to spin out a company from a university and the university license option agreement cover the contract steps.
- How wide is the funnel? Patents screened per company formed tells you more than the number of companies announced.
FAQ
Is a university venture studio the same as a technology transfer office?
No. The TTO patents and licenses the institution's IP and supports spinouts from the sidelines. The studio supplies an embedded team that builds the company. The CASRAI guide describes them as complementary functions increasingly deployed together.
Which university opened the first venture studio?
MIT. Proto Ventures opened in 2019 and MIT describes it as the first venture studio of its kind within a university. Its 2025 playbook is the reference other institutions now follow.
How long does a university venture studio programme take?
Tulane's Founder Lab runs six months per cohort. At MIT, the venture builder spends roughly six months on opportunity search before de-risking and team formation begin, so the full path to spinout is longer.
Can an outside entrepreneur join a university venture studio?
Yes, at programmes built on the entrepreneur-in-residence model. Tulane recruits experienced founders into paid EIR roles and pairs them with faculty technologies, and applications for later cohorts are sourced through its IP office.