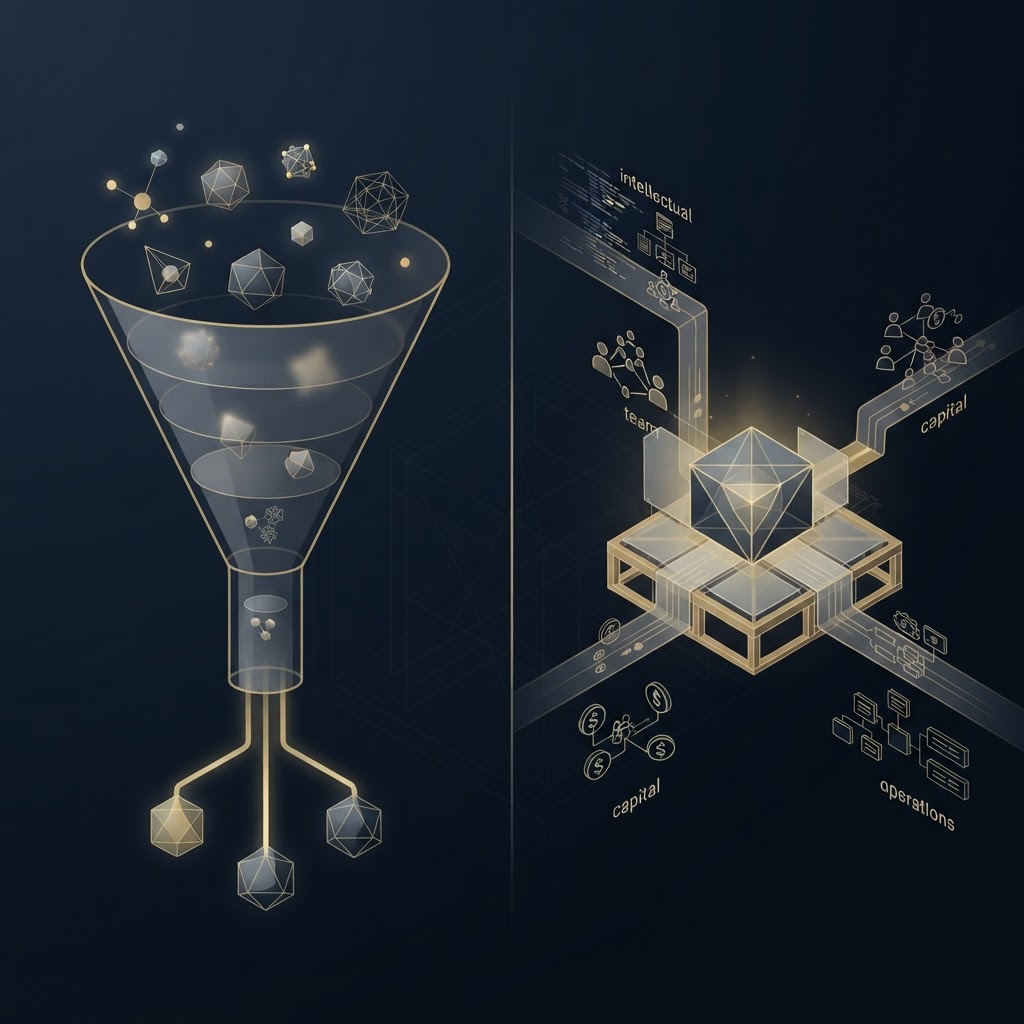
Most answers to venture builder vs venture capital start with an equity number. That gets it backwards. A venture capital fund sells selection: it picks from companies other people have already started. A venture builder sells creation: it turns an opportunity into a company that did not exist the week before. These are two different products. Comparing them on price alone is like comparing a contractor with a mortgage. This piece covers what each one sells, how each handles risk, how the choice looks from the founder's, investor's and corporate's seat, and why serious groups keep building and funding as separate disciplines. We write it as a builder. EX EPIC finances, patents and deploys deep tech, so some of the answers below come from our own work as well as from the research. ## Two different products Academic research on the model calls what a builder does "organizational co-founding". Builders step in before the startup exists and work inside daily operations. Venture capitalists come in later, once a company has been formed and tested in the market, and they support it through board seats and networks. The same research notes that builders usually hold a majority stake in what they create. One builder puts the dividing line well: a fund engages with a company, a builder engages with an opportunity. A fund's first decision is about selection: of everything that could be backed, which should be? A builder's first decisions are about creation: is the problem real, is it worth solving, and what would the company that solves it look like? | | Venture builder | Venture capital | | --- | --- | --- | | Core product | A company, built | Capital, allocated | | First decision | Should this exist? | Which of these wins? | | Starts from | An opportunity, often pre-founder | A formed team with evidence | | Daily role | Inside the operations | Board level | | Risk tool | Sequencing and staged capital | Diversification across many bets | | Typical stake | Often a majority at formation | Minority, round by round | If you need the model explained first, start with what a venture builder is. For the equity ranges and the ten-year fund clock in detail, see our breakdown of venture studio vs venture capital. We do not repeat those numbers here. ## What each one actually sells ### The fund sells capital and selection Venture capital is an asset class first. A firm raises money from limited partners, puts it into a portfolio of companies, and aims to return the fund through a small number of outsized outcomes. Its main product is money, plus advice, introductions and governance through a board seat. It is selective by design. Partners meet hundreds of companies to fund a handful, and the model depends on teams that are already moving. None of this is a weakness. A strong VC's skill is pattern recognition at scale. If your company already exists and the only thing holding it back is fuel, that skill is exactly what you want. ### The builder sells machinery A builder supplies capital too. What it mostly brings is the execution: strategy, product, engineering, go-to-market and operations, staffed by people who stay with the model from one venture to the next. A 2018 INSEAD study of the category describes builders as initiating ventures in-house, usually keeping a majority stake, and recycling teams, code, IP and customers across ventures until one succeeds. That recycling is the economic engine. The tenth company is cheaper to start than the first because most of the machinery already exists. The same study notes that the "idea" does not have to be invented in-house. Patents and research from universities or corporations are often the starting point. That detail matters for deep tech, as covered below. ## How each one handles risk Both models carry heavy risk. They manage it in opposite ways. A fund manages risk through portfolio construction. It expects most companies to underperform and lets a few outliers carry the result. A builder manages risk through sequencing: it validates before it creates, creates before it launches and launches before it scales, releasing capital in stages against evidence and stopping ventures that fail their tests early. That is the logic GCV describes in the comparison linked above. Do not mistake sequencing for safety. Mandalore puts it accurately: building does not eliminate risk, it moves it. There is less execution risk per venture and more concentration on each bet. A fund that loses one company out of thirty has a bad quarter. A builder that loses one of five has lost a real share of its year. ## Read it from your seat Most pages answer this question for founders only. Three different people actually ask it, and the right answer is different for each. ### The founder or scientist The founder scenarios in the Synapses piece hold up well. A repeat founder with a team, a working product and early revenue needs fuel, not a co-pilot, so a VC is the better fit. A scientist with breakthrough research but no commercial team, no product and no company yet usually needs the operational scaffolding a builder supplies. Paying a builder's larger stake makes sense only when the builder actually takes risk off the venture. If all you need is capital and autonomy, it is a bad deal. Before you sign, check how much equity venture studios take and what you get for it. ### The investor An investor is not choosing between being a fund and being a builder. The choice is which exposure to buy. BCG's work for sovereign wealth funds and pension plans counts more than 500 venture builders worldwide. They typically run ten or more companies at once, with first checks that can start as low as $50,000 and a target of a sale or listing within ten years. BCG is just as clear about the catch. Payoff can take five to ten years, which is why the model does not suit most private equity firms but can suit investors with a long horizon. For how that compares with a buyout logic, see venture studio vs private equity. The useful investor question is whether this builder's machinery compounds. Do its teams, IP and customer access actually carry from one venture to the next, or is each company a fresh start with a shared logo? ### The corporate Corporates sit in an odd position. Corporate venture capital buys minority stakes in outside startups. A corporate builder creates new companies, and the research cited above finds builders often aligned with a parent organization's strategy, drawing on its assets. If the goal is a window onto innovation, a CVC stake is cheaper. If the goal is to turn internal IP, customers or installed equipment into a standalone company that can raise outside money, that is a building job, and a check will not do it. ## Why build and fund stay separate The most interesting point in this SERP comes from a builder that also runs an investment arm. GCV keeps the two apart on purpose. It calls the separation a regulatory requirement, because its investing side operates under FCA regulation, and a clarity requirement, because building a company and funding one are different disciplines. That matches what we see. The two models are partners in sequence, not competitors. A builder does the earliest and hardest work, and venture capital then provides growth capital once there is a validated product and a working team. A builder's best output is a company a good VC wants to fund. When a builder starts acting like a passive fund, or a fund calls two associates a "platform team", founders end up with the wrong partner for the job they need done. ## Where deep tech forces the question In software, the builder vs VC choice is often a preference. In deep tech it is close to forced. SDTA makes the point that deep-tech risks are higher, the technology is more complex, and the capital and expertise needed are significantly greater. A lab result with no patent strategy, no operating team and no deployment path has nothing a fund can select. There is no company yet, only an opportunity. This is the work EX EPIC does as a deep tech venture builder. We find the technology, finance it, file the patents and build the team that deploys it. It shows in the record: a capital track record, Zero-X waste-to-energy systems with 200+ units deployed in 11 countries, 24 patent families filed through EX IX, and 250+ operators trained and placed across the portfolio through EX EPIC Academy. None of that started as something a fund could select. Each one began as an opportunity that had to be built first. ## Which one to call first Ask one question: what is the scarcest thing your venture needs right now? - Money. The team is in place, the product works and the constraint is fuel. Talk to funds. A good one will tell you quickly whether you fit.
- Capability. You can see the opportunity but not yet the company. Talk to builders. Raising capital first only buys time to find the gap more expensively.
- Both, in sequence. This is the common deep-tech path. A builder forms the company and then hands it to venture capital for growth. Then check the partner. Who does the work once the money clears? What is their track record in your domain? How do they behave when the plan breaks? Accelerators and incubators sit in between, offering programmes and space rather than co-founding; we compare them in venture studio vs accelerator vs incubator. ## FAQ ### Is a venture builder a type of venture capital? No. A builder often invests its own capital, but capital is one input. Its product is the company: it originates the venture, staffs it and runs early operations as a co-founder. A VC fund's product is capital allocated by selection across companies that already exist. ### Can a startup built by a venture builder raise venture capital later? Yes, and that is the normal sequence. The builder forms and de-risks the company, and outside VCs come in for growth rounds once there is a validated product and a functioning team. A builder that cannot get its companies funded by outside investors is showing a warning sign. ### Who was the first venture builder? idealab, founded by Bill Gross in Silicon Valley in 1996, is widely considered the first true venture builder, according to the INSEAD study cited above. Rocket Internet and betaworks followed in 2007. ### How long does a venture builder take to pay off for investors? Longer than most private capital is comfortable with. BCG puts the payoff at five to ten years, with portfolio companies aiming for a sale or listing within ten. That suits investors with a long horizon rather than funds that need fast liquidity.