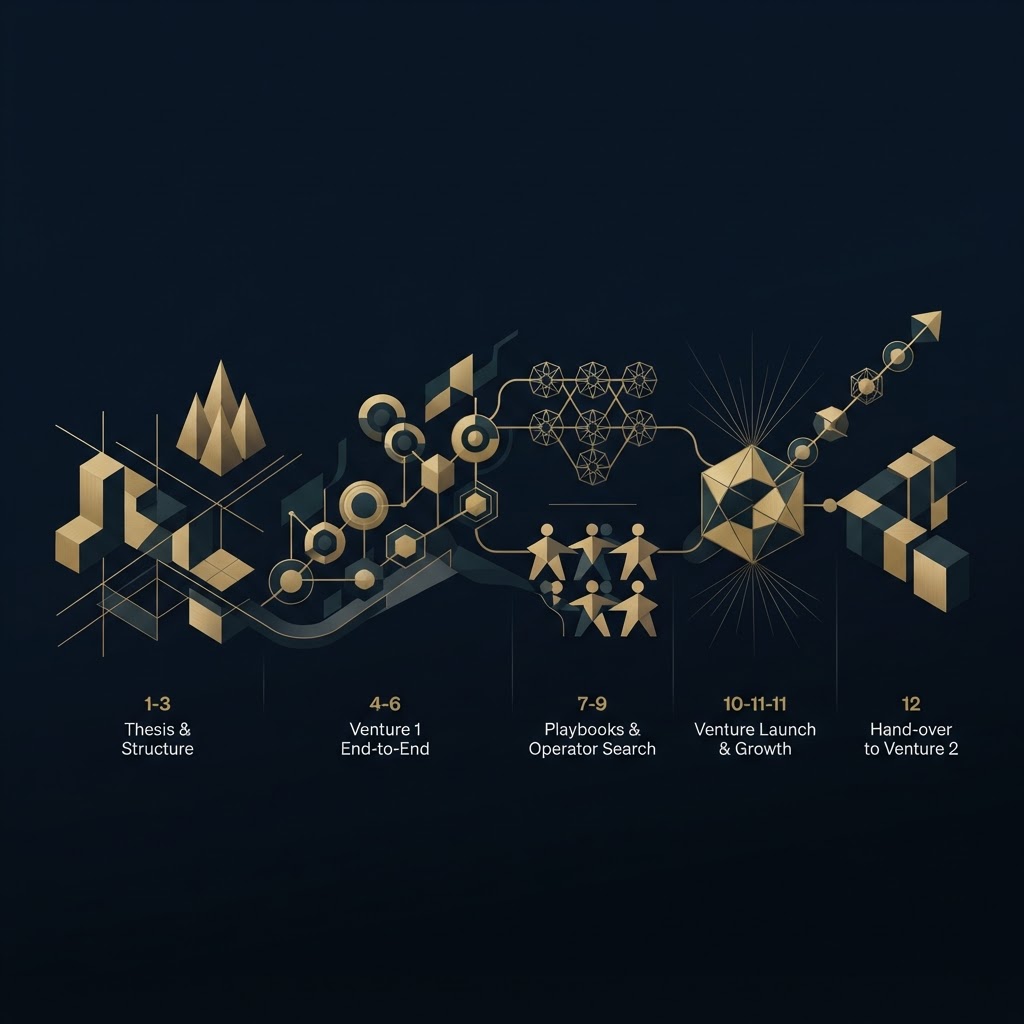
Most guides on how to start a venture studio hand you a checklist: define a niche, secure funding, build a team. True, and useless, because the hard part is the order and the price of each step. Get the sequence wrong and you spend two years and a few million building a logo with a portfolio page. We build companies on science for a living. EX EPIC finances, patents and deploys deep tech, and the studio machinery behind it is what this guide is about. If you need the definition first, start with what a venture studio is. This piece is for the person who has decided to build one and wants the playbook. ## Decide whether you should start one at all The model is popular. The number of independent and in-house studios doubled between 2018 and 2023, to about 870. The same MIT Sloan research names four conditions a studio needs to work: 1. Something proprietary to build on: specialised talent, an internal IP portfolio, or real market insight 2. A combination of those internal assets with external capabilities 3. The right governance mechanisms 4. A long-term commitment of time and money Be honest about number four. The authors also flag the two classic failure points: high studio equity that scares off strong founders and follow-on investors, and capital requirements that outrun what the studio actually has. If you cannot fund several ventures in parallel before any of them returns cash, you are about to start an expensive incubator. ## Step 1: Write the thesis, including what you refuse A thesis is not "B2B software" or "climate". It is the sectors, stages and buyers you will build for, and, just as important, the explicit refusals. Refusals are what let a small team say no fast. Then build the funnel the thesis feeds. The pipeline is the bottleneck nobody budgets for: one university studio says a studio must review 20 to 30 or more ideas for every company it creates. The same group launches 2 to 3 ventures a year from a pipeline of 100 or more ideas. That ratio is the real job. If your thesis cannot generate a hundred credible ideas, narrow it until it can, or widen your sources. ## Step 2: Size the capital honestly ### What a studio costs to run Here the SERP is full of round numbers, so take the better ones. One widely cited studio research report puts the floor at at least $1 to 2M, better $5 to 10M or more, with a median annual studio budget of $1.36M and an average of $2.49M in the GSSN 2022 data. The same research cites one European studio at roughly EUR 200K to take a single startup to the point where it can raise external seed, and notes that 79% of studios put starting capital into their companies, averaging $476K each. ### What each venture costs to get to seed People are the cost. MIT's R&D studio playbook puts it at about $500K per venture builder per year, covering salaries, operations and the prototyping and market work on each idea. Teams that reach the build phase get another $50 to 100K for roughly six months. Put it together for a first-generation studio: two or three senior builders, one venture end to end in year one, two more in year two, and capital reserved to write the first cheque into each. That is a seven-figure annual budget before anything returns. Plan two years of runway, and answer the year-two cash question in writing on day one, before it becomes urgent. ## Step 3: Pick the structure that matches the ventures ### Balance sheet or holding company Three structures dominate: a self-funded balance sheet, a studio plus a separate fund, and a holding company that owns ventures permanently. The self-funded route gives the most control and the most patience, and it is how most surviving studios start. The holdco suits durable, cash-generating companies but is harder to raise for, because you are asking for permanent capital. ### Studio plus fund (two entities) The scaled standard is two entities: an operating studio that holds founder equity and a fund that invests cash. The warning that matters: the wrapper has to match the ventures. A ten-year fund full of slow compounders will be forced to sell at bad moments, and a holdco full of companies that need eight-figure growth rounds will starve. ### Why management fees will not pay the bills The fund math is brutal at small sizes. On a standard 2% fee, a fund needs to be about $50M before the fee covers $1M a year of studio cost, and setting up a fund beside the studio runs $30 to 200K in legal fees (both from the inniches research above). Studios that have been at it for years say the same thing from the inside: management fees alone cannot carry a studio, so they offset burn with corporate partnerships and manage actively for early liquidity. Our breakdown of the venture studio business model goes deeper on revenue offsets. Our advice: start on the balance sheet, prove two or three builds, then raise the fund on a track record instead of a deck. ## Step 4: Hire operators before you announce anything A studio is its builders. Lehnert's version is three seats of judgment you cannot outsource: someone accountable for product and release quality, someone accountable for pipeline and go-to-market tests, and a decision owner who can rewrite the offer when customers push back. Contractors can carry ticket load. They cannot carry those seats. For science-based studios the profile is stricter. MIT describes the ideal venture builder as one third technical postdoc, one third startup founder, one third venture investor, committed full time for at least two years. They explicitly warn against hiring current researchers or MBAs without technical depth. A tough-tech studio playbook puts it more bluntly: hire for scar tissue, meaning former hardware founders, principal investigators from funded programs, and regulatory people. Start the operator search before you need anyone. Once you have a bench, design how it is shared across ventures. We wrote up the shared team model separately because it is where most studios either compound or break. ## Step 5: Set the equity terms before the first founder conversation Decide your terms before anyone asks. Across the market, studio equity ranges from 15 to 80%, often split as common shares for the studio's sweat and preferred shares for its cash. Where you land on that range is a strategy decision, not a negotiation tactic. Take too much and the next investor walks, which is exactly the Sloan warning above. Take too little and the studio cannot fund its own bench. Write it down: the stake for sweat, the stake for cash, vesting for the founding CEO, and what happens to the studio's position at Series A. Compare with how much equity venture studios take before you publish anything. ## Step 6: Run your first three builds, one at a time The most expensive mistake is launching three ventures at once to look like a studio. The first year should look like this, following the Inverse Collective sequence above: - Months 1 to 2: thesis, refusals, structure, and the year-two cash answer
- Months 2 to 5: one venture, end to end
- Months 4 to 8: write the playbooks while the lessons are fresh
- Months 6 to 10: start the operator search for venture two
- Months 9 to 12: hand over venture one, then start venture two Every build runs on the same ninety-day proof plan with kill criteria written before it starts, and you cap the number of active builds so senior hours stay real (Lehnert again). The test of whether you built a studio is simple: does venture two start with more than venture one had? A playbook, a template, a known-good hire. If not, you built a company with overhead. ## What changes when the studio builds on science Almost every guide on this SERP assumes software. Science-based studios fail for different reasons, and the setup has to account for three of them. IP timing. Patent decisions come before the company exists. At a research university, a provisional patent must be filed before the invention is disclosed in a paper or a conference talk, and the full utility filing follows within a year. A studio that only thinks about IP at incorporation has often already lost it. See our guide to the university venture studio for how the licence side works. Longer clocks. Some studios built on research IP avoid long cycles outright. NJII builds toward a financial milestone within 18 months and says outright that sectors with multi-year development or complex regulatory pathways are not a fit for its model. If your thesis is energy, carbon or biotech, your structure has to tolerate exactly those cycles, which pushes you toward the balance sheet or holdco and away from a short fund. A different shared layer. The shared services in a hard-tech studio are permitting, grant writing, manufacturing and regulatory work, not brand and growth. This is the studio we run. EX EPIC has a capital track record above financing, patenting and deploying deep tech, 200 or more waste-to-energy units across 11 countries, 24 patent families filed with around 100 more validated in the pipeline, and 250 or more operators trained and placed in the portfolio. None of those numbers came from a software playbook. They came from treating patents, public funding and field deployment as studio infrastructure. More in deep-tech venture builder. ## What the studio data does and does not prove You will be pitched these numbers, so know them. GSSN's survey of 258 studio startups reports that 84% reach a seed round and 72% of those reach Series A, against 42% for traditional startups, with 25.2 months from zero to Series A against 56. Use them carefully. A 2026 academic review of the studio literature warns that these figures may carry survivorship bias, because ideas killed in validation never enter the count, and that studios skew toward software, which grows faster anyway. The honest reading: studios can move faster when the process is real. The data does not prove that yours will. ## FAQ How much money do you need to start a venture studio? At least $1 to 2M to get going and ideally $5 to 10M or more, according to the studio research cited above. Budget two years of runway for the team and the first cheques before you count on any return. Can you start a venture studio without a fund? Yes, and most survivors do. Fund ventures from the balance sheet or a holding company, prove a few builds, then raise a fund on the track record if the ventures need one. How many startups should a new venture studio launch per year? In year one, one, end to end. Even established studios stay small: NJII launches two or three a year from a pipeline of more than 100 ideas, because each build needs real senior hours. Can a university or corporation start a venture studio? Yes. MIT's playbook places the studio inside an R&D group or a tech transfer office, with a managing director, executive sponsors, space and a dedicated budget. The builders still need to be full time.